For investors and taxpayers with complex portfolios
Your portfolio is complicated. Your return shouldn’t be wrong.
I’m an Enrolled Agent and a CERTIFIED FINANCIAL PLANNER™ professional with fifteen years in investments. I prepare tax returns for people who own stocks, bonds, REITs, mutual funds, ETFs, private notes, precious metals, equity compensation and cryptocurrency — and I understand what those things actually are before I type the numbers in.
Most investment tax mistakes aren’t errors on the return. They’re opportunities nobody knew to look for.
Does your tax preparer actually understand your portfolio?
Don’t take my word for it. Go and look at last year’s return. Here are three things you can check yourself in about five minutes.
Did anyone ask about your crypto separately?
The wash sale rule under Section 1091 applies to stocks and securities. Cryptocurrency is currently treated as property rather than a security, so the rule does not apply to it in the same way.
That means a loss-harvesting technique that would be disallowed on a stock position may be available on a crypto position. If your preparer handled both identically, nobody looked.
If you own bonds, is there any premium amortization?
Bonds bought above par carry a premium that can be amortized under Section 171, reducing your taxable interest each year and adjusting your basis as it goes.
On a substantial bond ladder this is real money every year, and it compounds because it changes what happens at maturity. If nothing on your return reflects it, either it wasn’t needed or nobody considered it.
Does your Schedule D show any cost basis marked “unknown”?
Securities acquired before the cost basis reporting rules took effect are reported as “noncovered,” and brokers often show no basis at all for them.
When basis is left blank, the entire proceeds get treated as gain. People pay tax on money they never made because reconstructing the basis looked like too much work.
None of these are exotic. They’re ordinary features of an ordinary portfolio, and they get missed constantly — not because preparers are careless, but because most of them have never worked on the investment side and don’t know to look.
What assets do you handle?
All of these, and the reporting quirks each one carries.
Stocks and ETFs
Qualified versus ordinary dividends and the holding periods that determine which is which. Specific identification against FIFO when you sell part of a position. Wash sales across accounts. Short and long-term character. The 3.8% net investment income tax that catches people the year they have a large gain.
Bonds and fixed income
Bond premium amortization. Market discount, which is ordinary income rather than capital gain and surprises almost everyone. Original issue discount and accrual. Accrued interest paid at purchase. Taxable municipals, private activity bonds that carry AMT exposure, and the de minimis rule that converts a small discount into ordinary income.
Mutual funds
Capital gain distributions you owe tax on even in a year the fund lost value. Buying a distribution shortly before the record date and paying tax on your own money. Basis in reinvested dividends, which people routinely forget to count and therefore overpay on when they sell.
REITs and real estate funds
Ordinary REIT dividends that qualify for the Section 199A deduction, which is frequently missed entirely. Return of capital distributions that reduce your basis rather than being taxed now, and therefore change what you owe years later. Non-traded REITs and their reporting.
Partnerships and K-1s
Publicly traded partnerships that generate filing obligations in states you’ve never visited. Basis tracking nobody kept. Section 751 ordinary income recapture when you dispose of units, which converts part of what you assumed was a capital gain. Passive activity limitations and suspended losses.
Metals, notes and the unusual
Physical gold and silver, and the ETFs holding them, are taxed as collectibles at a maximum rate well above the normal long-term capital gains rate. Private notes and seller financing carry imputed interest and original issue discount rules. Options, assignments and expirations. Foreign holdings with their own reporting.
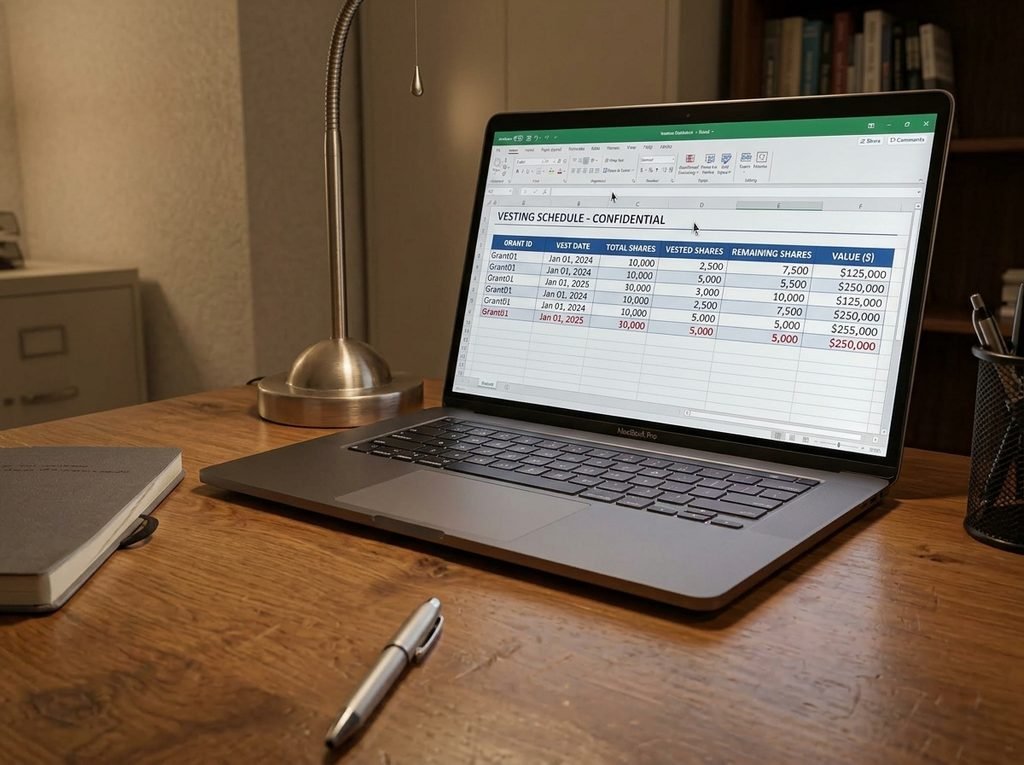
How is equity compensation taxed?
It depends entirely on which kind you have, and the four main types are taxed in genuinely different ways. Getting this wrong is expensive, and the mistakes usually happen at exercise or vest rather than on the return itself.
Incentive stock options (ISOs) create no regular tax when you exercise — but the bargain element is an alternative minimum tax preference item, which is how people end up with an AMT bill on stock they haven’t sold and can’t easily pay from. Hold long enough and the eventual sale gets capital gain treatment; sell too early and it becomes a disqualifying disposition taxed as ordinary income. There’s also an AMT credit that carries forward, which many people never claim in later years because nobody tracked it.
Non-qualified stock options (NSOs) generate ordinary income at exercise on the spread, reported through payroll. The basis question afterwards is where the errors cluster — double-counting income that was already on your W-2 is one of the most common investment tax mistakes there is.
Restricted stock units (RSUs) are income at vest. Employers commonly withhold at a flat supplemental rate that is well below the marginal rate of a high earner, which means a large vest can quietly create a substantial April shortfall that nobody warned you about.
Employee stock purchase plans (ESPPs) turn on whether the disposition is qualifying or disqualifying, and the discount is handled differently in each case. The brokerage 1099 frequently reports a basis that does not account for income already recognised, so people pay tax twice on the same dollars.
Also: the Section 83(b) election, which must be filed within 30 days of grant and cannot be fixed afterwards.
What is tax loss harvesting, and how much can it actually save?
Tax loss harvesting means realising losses on investments that have declined in value, and using those losses to offset capital gains elsewhere in your portfolio. Losses offset gains dollar for dollar, up to $3,000 of any excess can be applied against ordinary income each year, and anything left carries forward indefinitely.
The wash sale rule is where it goes wrong
If you buy a substantially identical security within 30 days before or after the sale, the loss is disallowed and added to the basis of the replacement. Most people know this much.
What catches people is the reach of it. The window is 61 days, not 30. It applies across all your accounts, not just the one you sold from. It applies to purchases by your spouse. And if the replacement is bought inside an IRA, the disallowed loss is lost permanently rather than deferred — one of the few genuinely irreversible mistakes in this area.
Automatic dividend reinvestment triggers it constantly, and almost nobody realises.
The other things worth looking at
- Gain harvesting in a low-income year, where long-term gains may be taxed at zero
- Which lots to sell, and specifically identifying them rather than accepting FIFO
- Where an asset is held — the same investment can cost you very different amounts in a taxable account than in a tax-deferred one
- Timing a large sale across two tax years instead of one
- Charitable gifts of appreciated securities rather than cash
- Carryforwards from prior years that nobody is tracking
- Whether the net investment income tax applies, and whether it can be managed
One boundary, stated plainly: I analyse the tax consequences of what you own and what you’re considering. I don’t tell you what to buy or sell, I don’t manage money, and I hold none of your assets. If you have an investment advisor, I work alongside them — and they’re usually pleased to have someone handling the tax side, because they aren’t licensed to.
Why does a CFP® doing tax returns matter?
Because the two halves of this are usually held by different people who never speak to each other.
I spent fifteen years in financial advice before I did anyone’s taxes. I’ve held CFP® certification since 2019, which required coursework across investments, retirement, estate planning, insurance and tax, a comprehensive examination, several years of qualifying experience, and an ongoing ethical commitment. Then I became an Enrolled Agent — the only tax credential issued by the federal government, carrying unlimited rights to represent taxpayers before the IRS.
What that combination buys you is recognition. When a K-1 arrives with Section 751 recapture buried in it, when a 1099 shows basis that can’t possibly be right, when a bond was bought at a premium, when an ISO exercise is about to create an AMT problem — I know what I’m looking at, because I spent fifteen years on the other side of it.
Both credentials require continuing education every year. Neither is something you earn once and stop studying.
Questions people ask
Do I need a CPA for investment taxes, or will an Enrolled Agent do?
Either can prepare your return. An Enrolled Agent is licensed federally by the U.S. Treasury specifically for taxation and representation, while a CPA licence is issued by a state and covers a broader accounting remit including audit and assurance work you almost certainly don’t need.
For investment tax specifically, what matters far more than which letters someone holds is whether they have actually worked with portfolios. Plenty of excellent CPAs have never dealt with a bond premium election or an ISO exercise, and plenty of Enrolled Agents have.
Does the wash sale rule apply to cryptocurrency?
Under current law the wash sale rule in Section 1091 applies to stocks and securities. Cryptocurrency is treated as property rather than a security for federal tax purposes, so the rule does not apply to it the same way. Legislation to change this has been proposed repeatedly and could pass at any time.
Because the position could change, and because the analysis depends on your specific holdings, this is worth confirming for your situation rather than acting on a general rule you read somewhere.
Why did I owe alternative minimum tax after exercising stock options?
Because incentive stock options create no regular income at exercise but the bargain element — the difference between the strike price and the fair market value on the day you exercised — is an AMT preference item. You can end up owing tax on a gain you have not realised, on shares you still hold, which is a genuinely difficult position if the stock then falls.
AMT paid on an ISO exercise generally creates a credit that can be recovered in future years. Many people never claim it, because it requires someone to track it across returns and nobody was.
My broker didn’t report cost basis for some of my shares. What now?
Securities acquired before cost basis reporting rules took effect are classified as “noncovered,” and brokers are not required to report basis on them. If basis is left blank on the return, the full proceeds are treated as gain — so you pay tax on money you never made.
Basis can usually be reconstructed from old statements, transfer records, historical prices, corporate action history, and reinvested dividend records. It’s tedious work and it is frequently worth thousands of dollars.
Are municipal bonds always tax-free?
No. Interest on most municipal bonds is exempt from federal income tax, but several categories are not. Some municipal bonds are federally taxable outright. Private activity bonds can carry alternative minimum tax exposure. Out-of-state bonds are often taxable at state level. And exempt interest still counts toward the calculation that determines how much of your Social Security is taxable.
Separately, a capital gain on selling a municipal bond is taxable regardless, and market discount on a bond bought below par is taxed as ordinary income rather than capital gain.
Will you tell me what to invest in?
No. I analyse the tax consequences of what you already own and of decisions you’re considering. I don’t recommend securities, manage portfolios, or hold client assets, and I receive no commission from anyone.
If you work with an investment advisor, I coordinate with them. That division suits everyone: they handle the portfolio, I handle the tax consequences, and nothing falls into the gap between the two.
Can you fix a prior year return if something was missed?
Often, yes. An amended return can generally be filed within three years of the original filing date or two years from when the tax was paid, whichever is later. If basis was omitted, a carryforward was lost, or income was reported twice, that’s recoverable within the window.
This is one of the more common reasons people come to me, and reviewing an old return is straightforward work that occasionally pays for itself several times over.
Send me last year’s return
Tell me roughly what you hold and what’s been nagging at you. If you’d like me to look properly, a review of last year’s return is usually the fastest way to find out whether anything was left behind.
Please don’t attach statements or your return here. Once we’re talking you’ll get a secure portal.
What happens next
A reply in a day
From me. I’ll usually be able to tell you from your description whether there’s something worth looking at.
A return review
I read last year’s return properly and send you a written summary of what I’d have done differently — including if the answer is nothing.
A fixed price
In writing before anything begins, with the scope set out. Basis reconstruction, if it’s needed, is quoted separately.
Then it’s ongoing
The useful work happens in the autumn, not in April. Harvesting, timing and carryforwards only help if someone looks before the year closes.
Michael Jones, EA & CFP® — Enrolled Agent, licensed by the U.S. Department of the Treasury to represent taxpayers before the IRS in all fifty states. This page is general information about tax rules, not advice about your specific situation, and it is not investment advice. Tax law changes; confirm anything here before acting on it.