About
You shouldn’t need four professionals to sort out one life.
A tax preparer who’s never seen your books. A bookkeeper who doesn’t do returns. A planner who won’t touch either. Nobody who’ll pick up the phone in July. I built this practice to be the one person who does all of it.
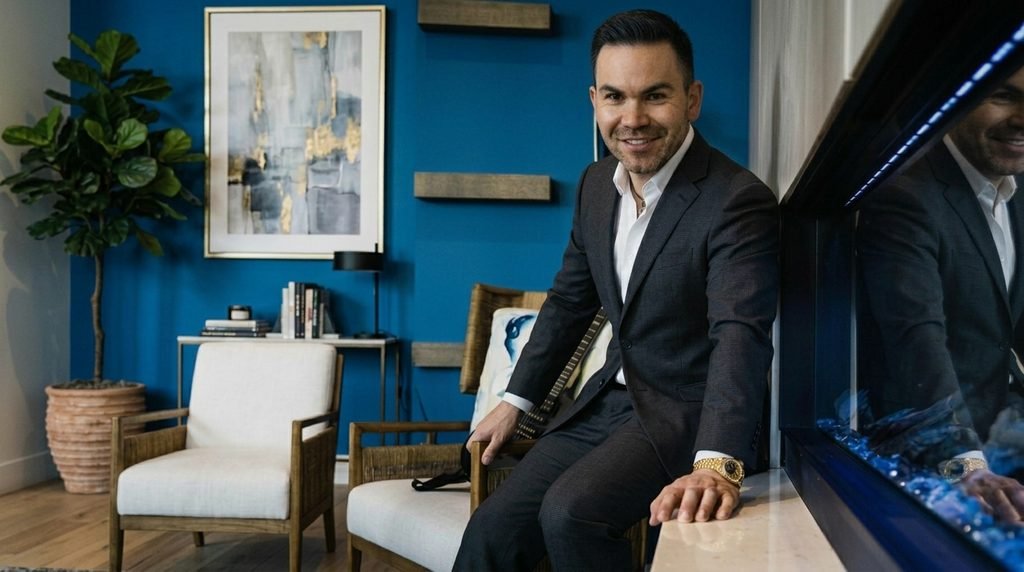
Michael Jones, EA & CFP
Fifteen years in financial advice. Three years running a business. One person who’s seen both sides of your problem.
How I got here
I’ve spent more than fifteen years in financial advice, and I’ve held the CFP® certification since 2019. For most of that time my job was helping people think about the long arc of their money — what they were saving, what they’d need, how it all fit together.
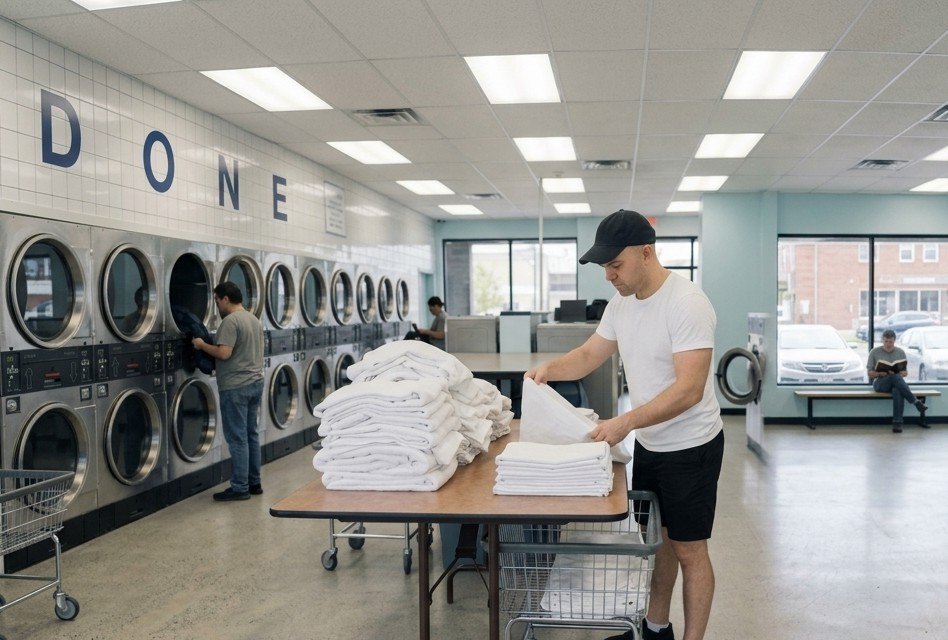
Then in 2022 I took over a laundromat that was failing.
I ran it, turned it around, and eventually sold it at a profit. It was the hardest work I’ve done. Coin counts, machine breakdowns at nine at night, utility bills that made no sense until I sat down and worked out why, a business that runs on cash in an era when nothing else does. I learned more about how a small business actually functions in three years of that than in the fifteen before it.
I also learned that I never had time for the paperwork. There was always something more urgent than reconciling a month of coin drops or working out whether an equipment purchase belonged in this tax year or the next one. So it waited. And waiting cost me money — not dramatically, not all at once, but steadily, in deductions I didn’t take and decisions I made a year later than I should have.
Both careers pointed at the same gap. In financial advice I kept running into tax questions I wasn’t licensed to answer. Running the laundromat, I was the person with the questions and no time to chase them down. So I went and got the credential that fixes both problems, and became an Enrolled Agent in 2026.
This practice is the thing I wanted and couldn’t find: somebody you can hand the messy, unglamorous, time-consuming parts of your financial life to, who actually understands what your business does all day, and who will still be reachable in July.
I’ve been the one with the shoebox full of receipts.
I’ve sat on your side of this desk, and I never had time for any of it either.
What my credentials actually mean
What is an Enrolled Agent?
An Enrolled Agent is a tax professional licensed directly by the U.S. Department of the Treasury. It is the only tax credential issued by the federal government, and it carries unlimited rights to represent taxpayers before the IRS in all fifty states.
In practice, that means three things. I can prepare any federal return, for any kind of taxpayer, anywhere in the country. I can speak to the IRS on your behalf and respond to notices in your name. And I can represent you through an audit, an appeal, or a collections matter from the first letter to the last, without needing to hand you off to someone else.
The credential is earned by passing a three-part examination covering individual taxation, business taxation, and representation practice, and by passing a suitability check on your own tax compliance and background.
What does the CFP® certification cover?
CFP® certification is issued by the CFP Board and requires coursework across the full range of personal finance, a comprehensive examination, several years of qualifying professional experience, and an ongoing ethical commitment.
The body of knowledge it covers is deliberately broad: retirement planning and income strategy, estate and legacy planning, education funding, insurance and risk, employee benefits, cash flow and debt, and tax planning across all of it. That breadth is why I can see how a tax decision connects to the rest of your situation rather than treating the return as a form to be filled in.
Digital assets and blockchain
I hold a Certificate in Digital Assets and Blockchain from the New York Institute of Finance. Crypto is one of the areas where tax reporting has moved faster than most practitioners have kept up with, and it’s a common reason people come to me after their previous preparer told them they’d rather not.
Both credentials require continuing education every year
Neither of these is a certificate you hang on a wall and forget. Enrolled Agents must complete 72 hours of continuing education every three years, with a minimum every single year and mandatory ethics training. CFP® certificants must complete 30 hours every two years, also including ethics.
Tax law changes constantly, and a practitioner who stopped studying five years ago will cost you money without ever knowing it. The requirement is the floor, not the ceiling — but it does mean that anyone still holding these credentials has been keeping up.
What you can bring to me
Most of these aren’t really tax problems. They’re the thing you’ve been meaning to deal with, the conversation you don’t know how to start, or the envelope you’ve been walking past. Any of them is a fine reason to call.
You’re pretty sure you’re overpaying
Nobody sends a letter telling you that you paid too much. You file, you hope, and you never find out. I’ll read last year’s return and tell you plainly what I’d have done differently — including if the answer is nothing.
Personal tax returns, advice and planning
Worried you won’t find out you did it wrong until it’s expensive
Entity structure, owner compensation, quarterly estimates, what you can and can’t run through the business. Most owners are guessing at all of it and won’t discover the guess was wrong for two or three years.
Business tax returns, advice and planning
There’s a box. You know what’s in it. You keep not dealing with it.
Every month you tell yourself this is the month. It never is, because there’s always something more urgent than data entry. Hand it over and stop carrying it around.
Monthly bookkeeping and catch-up
The bank balance went up. That doesn’t mean it’s working.
Is the second store actually profitable, or is the first one carrying it? Are your utilities normal for your volume? Buy the machines or finance them? I ran a laundromat. I know which numbers tell you something and which ones just look busy.
Business planning and advice — laundromats especially
It’s been on the counter for four days and you haven’t opened it
You know it’s from the IRS. You’ve been walking past it. Send it to me and I’ll tell you what it actually says, which is almost always less alarming than what you’ve been imagining.
IRS notices, audits and collections
Nobody will give you a straight answer about whether you’ll be all right
Not a forty-page projection built on assumptions nobody can defend. A clear look at what you have, which account it should come out of first, and what each of those choices costs you in tax.
Retirement savings and income planning
You can’t ask your parents about this without sounding like you’re counting the inheritance
You’re not being greedy. You just don’t want the family torn apart later over paperwork nobody could find. So blame me — tell them your tax guy says you have to ask, and I’ll ask the questions for you.
Estate, legacy and family planning
You’re getting married and neither of you wants to bring up money
Debt, credit, student loans, what happens to your filing status, whether either of you should talk to a lawyer. Somebody has to start that conversation, and it doesn’t have to be one of you. I’ll run it.
Before you get married
Health costs are the thing most likely to undo the plan
HSAs and what they’re actually for. Medicare surcharges that catch people out two years after the income that caused them. What’s deductible when a parent needs care, and what isn’t. The part of health costs that lands on a tax return.
Healthcare and benefits planning
You have policies. You’ve never checked whether they’d do what you think.
Most people buy coverage once and never look again. I’ll go through what you have, tell you where the gaps are and how any of it is treated for tax — and since I sell no insurance, there’s nothing I’d rather you bought.
Protection and risk management
Your last preparer said they’d rather not deal with the crypto
Four years of exchange exports, a wallet you’d half forgotten, staking rewards nobody explained, and no real idea what you owe. I hold a certificate in digital assets from the New York Institute of Finance and I’m not squeamish about it.
Cryptocurrency and digital assets
There’s an offer on the table and the tax bill decides what you actually keep
Asset sale or stock sale, how the price gets allocated, whether spreading it over years helps or hurts. These are decided before the paperwork is signed, and afterwards is too late. I’ve sold a business. Bring me the deal early.
Buying or selling a business
Not on the list? Ask anyway. If it isn’t something I do, I’ll tell you who does.
How I work, and why
Flat fees, agreed before I start. You get a fixed number in writing, not an hourly meter running in the background while you wonder whether it’s safe to ask a follow-up question.
Prices published on this site. You can work out roughly what this costs before you ever speak to me. Almost nobody in my field does this, and I think that’s a failure of nerve rather than a real difficulty.
I sell no products and manage no money. There is no commission behind any recommendation I make, no fund I’d rather you bought, and no assets under management. I get paid for my time and my judgement, and nothing else.
One person on every file. Not a rotating staff, not an offshore preparation team, not whoever happens to be free in April. You will always know exactly who did your return, because it’s the same person you talked to.
What I don’t do
Knowing where somebody’s limits are is more useful than any adjective they could use about themselves. So here are mine.
I don’t run your payroll. Trust fund tax liability is personal and unforgiving, deadlines don’t flex, and the margin doesn’t justify the risk to either of us. I’ll get you set up on a proper payroll platform, make sure your owner compensation is defensible, and handle anything the IRS sends you about it — but somebody else presses the button.
I don’t give advice on investment securities. I won’t tell you what stocks to buy, what to sell, or how to allocate a portfolio. I’ll happily tell you the tax consequences of something you’re already considering, which is a different question and usually the one that actually matters.
I don’t sell insurance or anything else on commission. No annuities, no policies, no products of any kind. Nothing I recommend pays me a referral fee.
I don’t trade or hold your money. I never take custody of client funds. Your accounts stay where they are, in your name, under your control.
I don’t promise pennies on the dollar. You’ve seen the advertisements. Most people who respond to them don’t qualify for what’s being advertised, and the firms running them know it. If you owe the IRS money, I’ll pull your transcripts and tell you what your actual options are — which are often better than you feared and rarely as good as a radio commercial.
It’s one person. Here’s what happens if something happens to me.
This is a solo practice, and that’s deliberate — it’s why the person who understands your file is the person who answers the phone. But it’s a fair question to ask what happens if I’m ill, or unreachable, or hit by something unexpected in the middle of March.
So I’ve arranged for it. Another Enrolled Agent has a standing agreement to step in and cover my clients if I can’t. Your records are backed up continuously and stored securely, so nothing depends on one computer or one person’s memory. If the worst happened, your return would still get filed and your file would go to somebody qualified to pick it up.
Most solo practitioners never mention this. I’d rather tell you plainly that I’ve thought about it.