For business owners
You’ve been saving up questions since March.
Most owners only speak to their accountant once a year, in the busiest month of that accountant’s life, about a return covering a year they can no longer change. Everything they wanted to ask gets compressed into twenty minutes, or never gets asked at all.
I keep your books, file your returns, and answer the phone in July. Same person for all of it, which means you never have to explain your business twice.
The ones you’ve probably been carrying around
Am I paying myself the right way, or just the way I started?
Should I be an S-corp? Somebody at a barbecue said I should.
Why did I owe so much in April when the year didn’t feel that good?
Can I actually deduct that? I’ve been assuming yes.
My partner and I never wrote anything down. Is that a problem?
Is this business actually profitable, or does it just feel busy?
None of these are April questions. They’re the reason people end up guessing for years at a time.
You shouldn’t need three people to run one business.
Most owners end up with a bookkeeper who doesn’t do taxes, a tax preparer who has never seen the books, and nobody at all who can answer a question between May and December. Then they spend their own evenings stitching it together and hoping the pieces line up.
I do all of it. Monthly bookkeeping, the business return, your personal return, quarterly estimates, and the IRS if it ever comes to that. One person who already knows your numbers, so you’re not starting from the beginning every time something comes up.
What I handle
Bookkeeping, so the numbers exist before you need them
Monthly reconciliation, sensible categorisation, and a profit and loss statement that actually tells you something — split by location or revenue line if that’s what your business needs.
Behind? That’s the usual case. Cleanup is quoted as its own project and it’s often the single most useful thing I do for a new client, because everything downstream depends on it. Nobody can advise you well from books that aren’t right.
Clean books also make your return cheaper to prepare, which quietly pays for a chunk of the bookkeeping.
Entity structure — the decision most people make once and never revisit
Sole proprietor, LLC, partnership, S-corporation, C-corporation. Most owners chose theirs at the start on somebody’s casual advice and have never looked again, even though the business is now a completely different size.
The right answer depends on your profit, how much you take out, whether you have partners, whether you plan to sell, and what state you’re in. It changes as the business grows. I’ll run the numbers rather than telling you what usually works, because “usually” is how people end up paying for a structure that doesn’t fit them.
If you’re starting something, this is worth thirty minutes before you file anything. Undoing an entity choice is far more expensive than making it correctly.
S-corp analysis and what to actually pay yourself
Two separate questions, and people usually only ask the first one.
Is the election worth it? Below a certain profit level it costs more in payroll administration and filing fees than it saves. Above that level it saves real money. I’ll tell you where you actually sit rather than reciting a rule of thumb.
What’s a reasonable salary? If you’ve elected S-corp status, the IRS expects reasonable compensation before distributions — and “reasonable” is a facts-and-circumstances test that most owners have never had documented by anyone. Paying yourself too little is one of the most reliably examined issues in small business tax.
I run the analysis and write it down, so if it’s ever questioned there’s a defensible file instead of a shrug.
Partnerships, and the paperwork nobody wrote
Partnership returns, K-1s, capital accounts, guaranteed payments, and how profit actually gets split when what you agreed verbally doesn’t match what the return says.
The recurring problem: two people started something on a handshake, put in different amounts of money and wildly different amounts of time, and never wrote down what happens if one of them leaves. Basis gets tracked badly or not at all, and then somebody wants out and nobody can agree what they’re owed.
I’ll sort out the tax side of that — including the elections that matter when a partner comes in or goes out — and tell you when you need an attorney rather than an accountant.
Corporate returns
1120 and 1120-S, filed on time and reconciled to the books rather than assembled from a spreadsheet in March.
If you’re a C-corporation: whether that’s still the right choice, how to get money out without paying tax on it twice, the reasonable compensation question running in the opposite direction, and what happens to accumulated earnings that just sit there.
Quarterly estimates that stop the April surprise
The most common preventable problem I see. You had a good year, nobody adjusted anything, and April arrives with a number you weren’t expecting and penalties on top.
There are safe-harbour rules that protect you from penalties even when the year turns out better than expected — but only if somebody sets them up deliberately. I recalculate as the year goes rather than once at the end, so the number in April is one you already knew about.
Buying or selling
Buying: I’ll go through the seller’s numbers before you commit, and structure the purchase so the price allocation works in your favour for the next several years rather than against you.
Selling: asset sale or stock sale, how the consideration is allocated, whether spreading payments over years helps. These are decided before signing, and afterwards is too late. Bring me the deal early — I’ve sold a business myself.
I’ve run one of these too
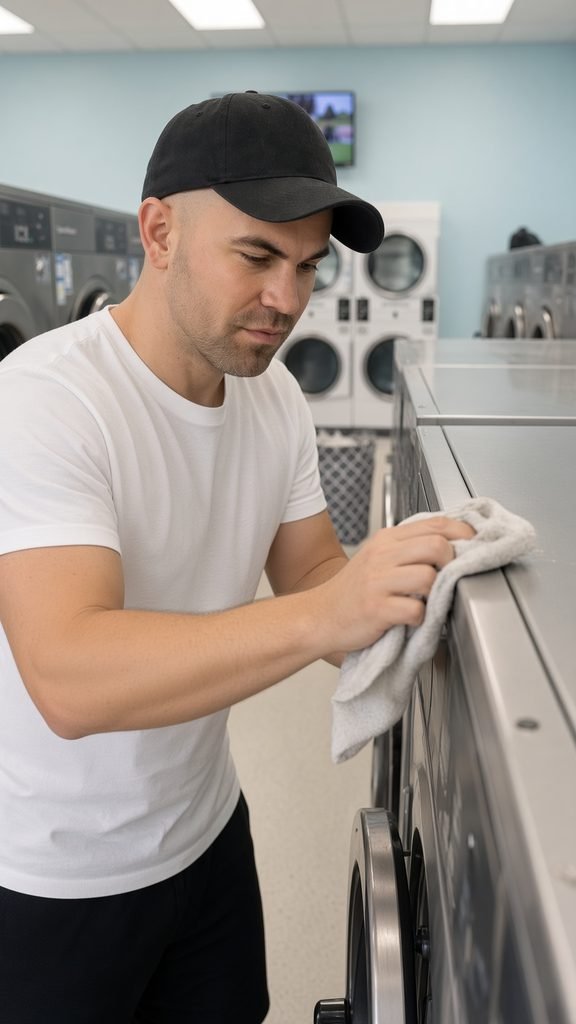
I spent fifteen years in financial advice, and then I bought a laundromat that was failing. I ran it, turned it around, and sold it at a profit.
What I learned from that has nothing to do with laundry. It’s that there is never time for the paperwork, because there is always something more urgent than reconciling last month. It waits, and waiting costs money — not dramatically, not all at once, but steadily, in deductions nobody took and decisions made a year later than they should have been.
That’s why I became an Enrolled Agent, and it’s why this practice is set up the way it is. Flat fees so you’re not watching a meter. Books and taxes together so nothing gets lost between two people. Reachable in July, because that’s when the questions actually happen.
Tell me about your business
What you do, how it’s set up, and what’s been bothering you. A few lines is plenty.
You don’t need your books in order to send this. If they were in order you probably wouldn’t be reading this page.
Please don’t attach financial statements or account details here. Once we’re talking you’ll get a secure portal.
What happens next
A reply in a day
From me, not an assistant.
Half an hour on a call
Mostly me asking questions. Bring the list you’ve been saving up — that’s what it’s for.
A fixed price, in writing
Before anything starts, with the scope written down. Cleanup, if you need it, is quoted separately so you can see what’s what.
Then it runs
Books monthly, estimates quarterly, returns annually, and a standing invitation to ask me things in between.
Michael Jones, EA & CFP® — Enrolled Agent, licensed by the U.S. Department of the Treasury to represent taxpayers before the IRS in all fifty states. This page is general information, not advice about your specific situation.